For US buyers financing with an SBA 7(a) loan
Your loan is sized on the QoE’s adjustments. Make sure they’re right.
An independent, buyer-side review of every adjustment in the lender’s quality of earnings report, in both directions. US$3,500, fixed. Back within 3–5 business days.
For US buyers financing an acquisition with an SBA loan. The lender’s QoE turns the seller’s figures into the earnings your loan is sized on, and every add-back it accepts, cuts or misses moves that number. We test each one from your side: add-backs the evidence supports that the report left out, and ones it accepted that it shouldn’t have. Within three to five business days of receiving the full report and supporting documents, you know what the figure rests on, what it means for your loan and equity, and what to raise before you sign.
Book a free 20-minute callNext available start: Tue 27 OctUS$3,500 fixed, paid in advance
Not ready for a call? Get the example Deal Screen, freeBefore you book
Four questions buyers ask first
01
What does the QoE Review provide?
A fixed list of checks on the lender’s report, read from your side of the table.
- Whether the report’s adjusted EBITDA ties back to the financial data it was built from
- Every adjustment it makes, and the ones it leaves out, with what each does to the figure
- Where the lender’s figure differs from the seller’s, and why
- What the lender’s figure means at your price: debt-service cover, your equity injection and any seller note
- Working capital and debt-like items the report raises
- Priority questions for the seller and the QoE provider, most important first
- What the report did not test
02
The lender already ordered a QoE. Why pay for a second read?
Because it was written for the lender, and its job is to protect the loan. Lender-commissioned QoEs are built to be cautious: when the evidence for an add-back isn’t in front of the provider, it usually comes out. Every add-back that comes out lowers the earnings your loan is sized on, which can mean more of your own money in the deal.
We go through the adjustments from your side, looking for the ones the report missed or cut that the evidence supports. Typical examples:
- Costs of the sale itself, such as broker, legal and accounting fees, expensed in the year
- One-off costs: a settled dispute, severance, a recruitment fee, a move to new premises
- The owner’s personal costs run through the business: vehicles, phones, travel, insurance
- Family members on payroll who won’t stay after the sale, net of what it costs to replace their work
- Equipment or repairs expensed that should have been capitalised
- Revenue or costs booked in the wrong year
And we test it the other way too. If the report accepted an add-back the evidence doesn’t support, you need to know before you take on a loan sized on it.
The review is addressed to you, not the lender. Where we find adjustments the evidence supports, you get the schedule and the evidence to raise with the lender and its QoE provider. Whether they accept them is their call.
03
Will this hold up my closing?
No. The review comes back within 3–5 business days of receiving everything it needs: the full QoE report with its schedules, the general ledger and the supporting documents behind the adjustments (invoices, payroll records, contracts), plus your LOI and financing terms. Then one call. It needs the full report, not a summary, and testing an add-back takes the evidence behind it. If you only have a summary, or don’t have the ledger yet, we’ll tell you exactly what to ask for.
04
Who do you work for?
You. We’re engaged by you, through the company that’s buying the business, and the review is addressed to you alone. We never act for the lender, the seller or the QoE provider on the same deal, and we have no stake in whether it closes.
How the services fit together
Where the QoE Review fits
Who you’ll work with
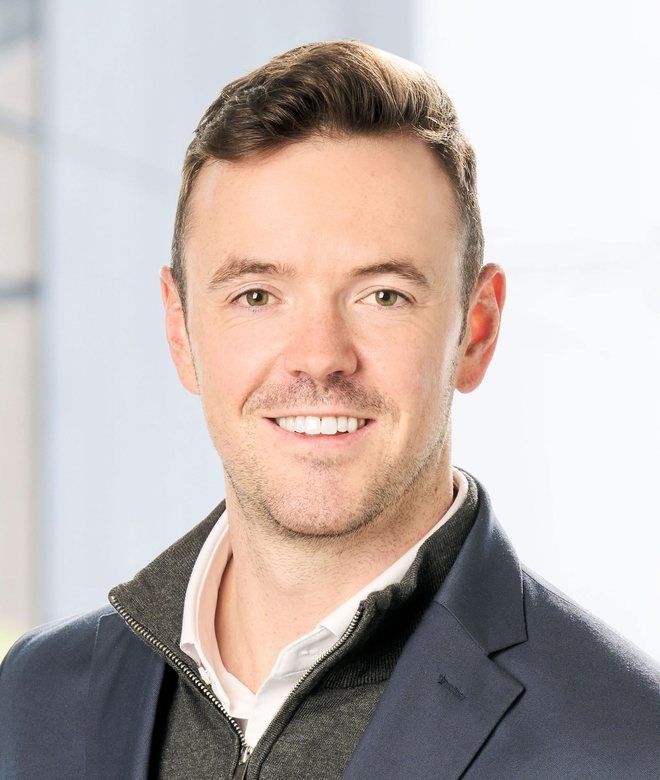
Will Stevenson ACA
Ex-Big Four Deal Advisory · Chartered Accountant
Will is a Chartered Accountant (ICAEW) with nine years of experience across audit, financial due diligence and deal advisory, including work at PwC, Grant Thornton and KPMG.
He has worked on buy-side and sell-side due diligence for private-equity-backed and mid-market deals of £30m–£100m, helping buyers and investors understand the numbers behind a deal and the risks that matter.
At Skerryvore Advisory, he brings that experience to smaller-business acquisitions, helping investors gain the same clear picture of what they’re buying before they commit.
Free example
See how we read a seller’s numbers
The example Deal Screen shows the same approach on a fictional business: every add-back tested against the evidence, in plain terms.